
Online Borrowing Considerations for Canadian Seniors and Retirees
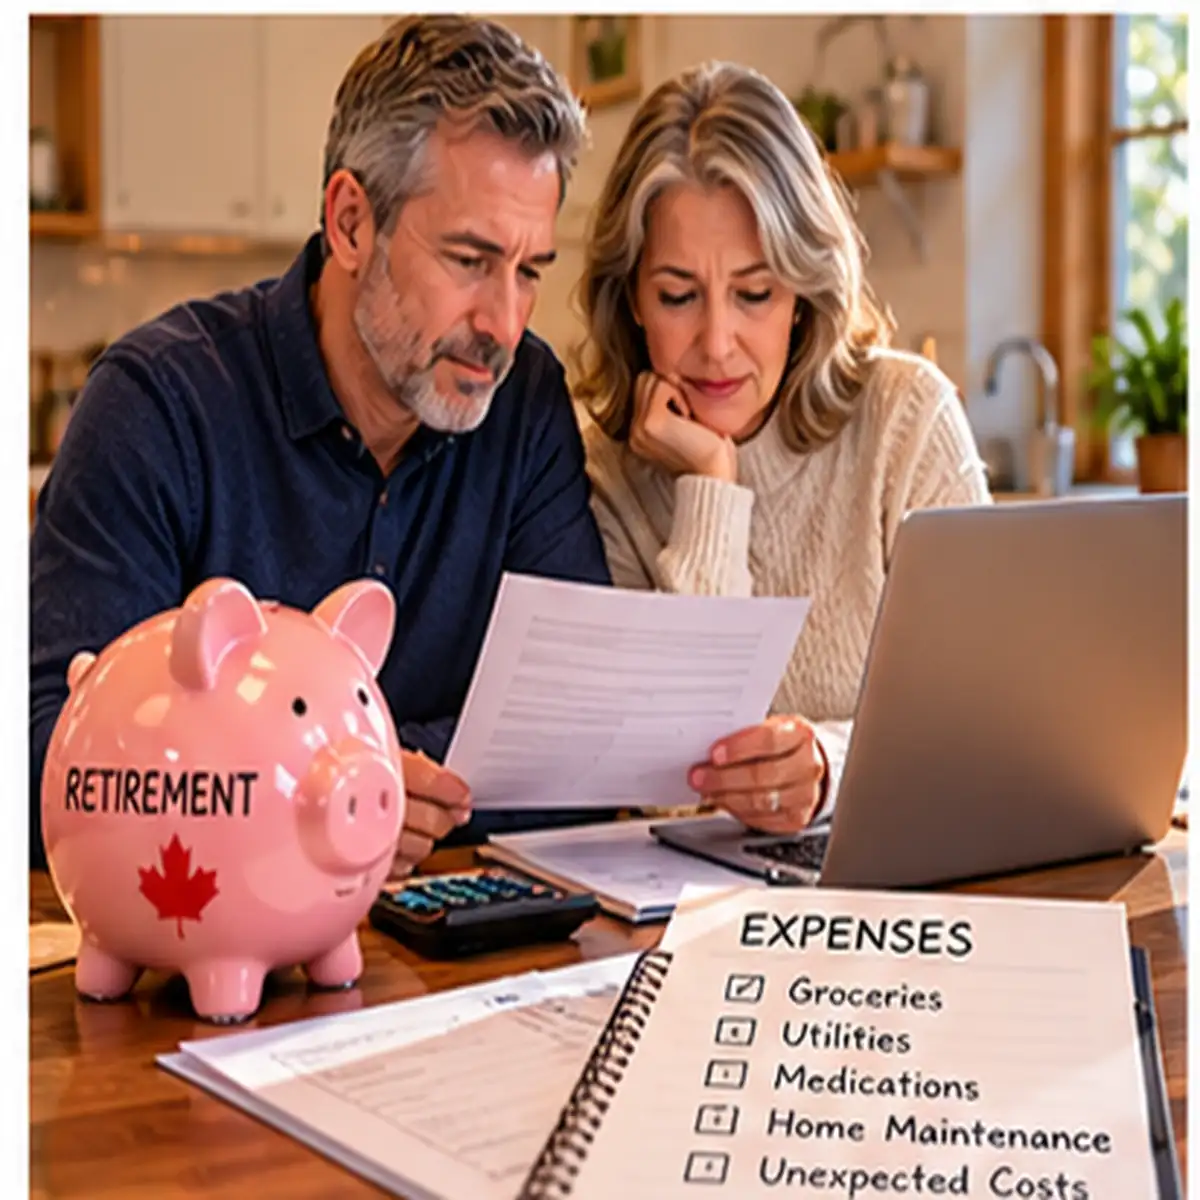
 Retirement often brings significant changes to household finances. Instead of receiving employment income, many Canadians rely on pensions, government benefits, personal savings, and investment income to manage their expenses. When an unexpected household cost arises, some retirees begin comparing borrowing options from Alberta lenders to understand what financing might be available. Before accepting any loan, seniors should evaluate their income sources, repayment affordability, and alternatives that may better protect their retirement savings.
Understanding Income During Retirement
Retirement income can come from several sources.
Eligible Canadians may receive Canada Pension Plan or Quebec Pension Plan benefits, Old Age Security payments, employer pensions, or income from registered savings.
Some retirees also receive investment income or continue working part-time.
These income sources may arrive according to different payment schedules.
Certain amounts can change because of benefit adjustments, withdrawals, or investment performance.
Creating a clear picture of reliable monthly income is essential before accepting a new financial obligation.
Why Unexpected Expenses Can Be Challenging
Although retirement may reduce certain employment-related costs, many household expenses continue.
Housing, groceries, transportation, insurance, and utilities remain necessary.
Some retirees also face additional expenses involving home accessibility, mobility equipment, or property maintenance.
An older home’s heating system may require replacement, or an essential appliance could stop working.
When savings are limited, these expenses can create financial pressure.
However, obtaining expensive short-term financing may reduce the income available for other necessities.
Do Lenders Accept Pension Income?
Some lenders consider pension or government benefit income when evaluating applications.
The types of income accepted depend on the financial institution and loan product.
Applicants may need to provide banking records, pension statements, or other documentation.
Age alone does not determine whether someone qualifies for every type of credit.
Lenders generally evaluate eligibility according to their policies and applicable legal requirements.
Seniors should be cautious about advertisements suggesting that approval is guaranteed simply because they receive government payments.
Evaluating Fixed-Income Affordability
A fixed or relatively predictable income can make budgeting easier, but it may also leave limited flexibility for unexpected expenses.
Before accepting a loan, determine how much income remains after essential costs.
Consider upcoming annual obligations such as insurance renewals or property taxes.
A repayment that seems manageable during one month may become difficult when several expenses arrive together.
If a loan would require withdrawing additional retirement savings or missing essential payments, it may not be appropriate.
Comparing Borrowing Products
Different financial products may offer different costs and conditions.
Personal instalment loans generally provide structured repayments.
An existing line of credit might offer another option for eligible borrowers.
Secured borrowing products can involve additional risks because assets may be pledged as collateral.
Payday loans typically involve high borrowing fees relative to their short terms.
Retirees should compare the total repayment amount, interest charges, fees, and consequences of missed payments.
A lower monthly payment does not always mean a lower overall borrowing cost.
Protecting Against Financial Fraud
Seniors, like consumers of all ages, can be targeted by fraudulent lending advertisements.
Scammers may promise guaranteed approval, request unusual advance payments, or impersonate legitimate financial institutions.
Be cautious about unsolicited telephone calls and messages offering loans.
Verify business credentials independently before submitting personal information.
Never provide security codes or online banking passwords to suspicious contacts.
Trusted financial professionals or family members may help review complicated offers when the individual wants that assistance.
Investigating Benefits and Assistance
Some retirees may qualify for additional federal, provincial, or community support.
The Guaranteed Income Supplement, for example, provides additional assistance to eligible low-income seniors receiving Old Age Security.
Other programs may help with certain housing or health-related expenses.
Eligibility varies, so current program requirements should be checked directly.
Accessing available benefits may reduce the need for borrowing.
Maintaining Long-Term Retirement Security
Retirement planning involves balancing current needs with the resources required for future years.
Unexpected expenses should be evaluated within that broader context.
Before borrowing, seniors should consider the effects on savings, monthly income, and financial independence.
A carefully selected financing arrangement may be manageable in some circumstances, but expensive recurring debt can place retirement security at risk.
Preserving adequate savings and reviewing lower-cost alternatives are important priorities for Canadians living on retirement income.